Ordinance or Law Coverage Florida is a policy add-on every homeowner should understand. Owning a home in Florida means preparing for more than just hurricanes. Building codes continue to evolve, especially in areas vulnerable to severe weather. If your home is damaged and needs repairs, you may be required to rebuild portions of the property to meet today’s construction standards not the standards that existed when your home was originally built.
That’s where Ordinance or Law Coverage can make a significant difference.
What Is Ordinance or Law Coverage Florida?
Ordinance or Law Coverage is an optional or included endorsement on many homeowners insurance policies that may help pay for the additional costs associated with rebuilding or repairing a home to comply with current local building codes after a covered loss.
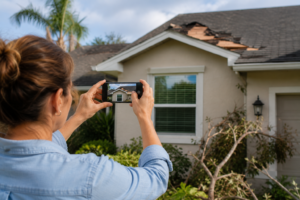
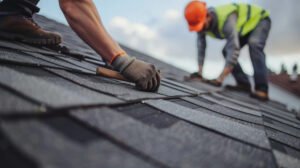
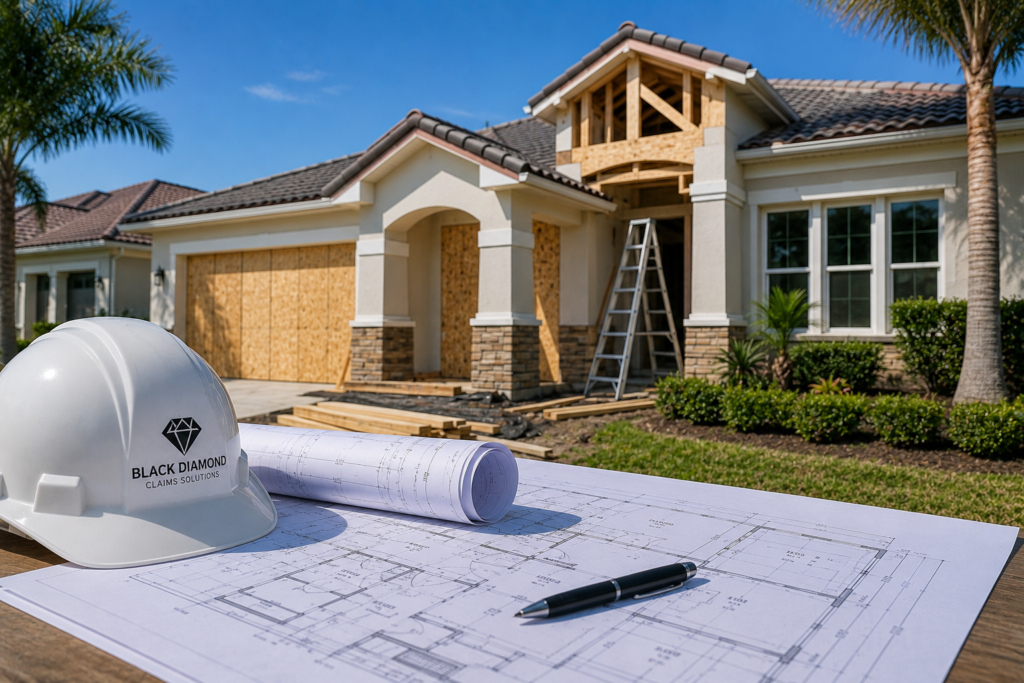
For example, if a hurricane damages a roof that was originally installed 20 years ago, local building codes may require upgrades that were not part of the original construction. While your standard homeowners policy may cover the direct damage caused by the storm, the additional costs required to meet today’s code requirements may only be covered if your policy includes Ordinance or Law Coverage.
Coverage varies by policy, so homeowners should review their specific insurance policy to understand what is included.
Why Is This Important in Florida?
Florida’s building codes have become more stringent over the years to improve the safety and resilience of homes against hurricanes, high winds, and other natural disasters.
Common code-required upgrades may include:
- Stronger roof-to-wall connections
- Improved roofing materials
- Enhanced structural components
- Updated electrical systems
- Modern plumbing requirements
- Wind-resistant windows or doors
If these upgrades are required after a covered loss, they can significantly increase repair costs. This is exactly the situation Ordinance or Law Coverage Florida is designed to address.
How Can Homeowners Prepare?
While no one expects to experience property damage, taking a few proactive steps can help simplify the process if a loss occurs.
Consider keeping:
- Copies of renovation permits
- Contractor invoices
- Roof replacement records
- Inspection reports
- Before-and-after photographs of major home improvements
Maintaining organized records can help establish your home’s condition before a loss and support discussions about necessary repairs.
Why Accurate Estimates Matter
Repair estimates do more than calculate material and labor costs. A detailed estimate identifies the scope of repairs, documents damaged building components, and helps all parties better understand the work needed to restore the property.
If building code upgrades are required, having accurate documentation can make it easier to identify where additional work may be necessary.
How Black Diamond Claims Solutions Can Help
Black Diamond Claims Solutions works alongside homeowners, contractors, attorneys, and licensed public adjusters by providing professional estimating, documentation support, appraisal reports, and other property claim services.
While Black Diamond is not a public adjusting firm, our team helps organize the information needed to support an efficient and well-documented claims process.
Final Thoughts
Building codes continue to evolve to make Florida homes safer and more resilient. Understanding whether your homeowners insurance policy includes Ordinance or Law Coverage Florida before a loss occurs can help you better prepare for unexpected repairs and avoid surprises during the rebuilding process.
If you have questions about your policy, speak with your insurance agent to understand your coverage and whether additional protection may be appropriate for your home.
Frequently Asked Questions
Does every homeowners insurance policy include Ordinance or Law Coverage?
Not always. Coverage varies by insurer and policy. Review your declarations page or speak with your insurance agent to determine whether your policy includes this coverage.
Does Ordinance or Law Coverage pay for all renovations?
No. It generally applies when a covered property loss triggers repairs that must comply with current building codes. Coverage depends on the policy terms and the circumstances of the loss.
Can building codes increase repair costs?
Yes. Updated building codes may require additional materials, labor, or construction methods that were not part of the home’s original design.
Disclaimer: Black Diamond Funding Ventures, LLC is not a public adjuster, insurance adjuster, law firm, or claims representative. Submission of information through this website does not create a client, agency, or fiduciary relationship. We do not negotiate, adjust, or settle insurance claims. Any information provided is for general educational purposes only and is not intended as legal advice or claim adjustment services. We may recommend licensed professionals where appropriate.
Sources
- Florida Building Code – https://www.floridabuilding.org
- FEMA – Building Codes Save: https://www.fema.gov